
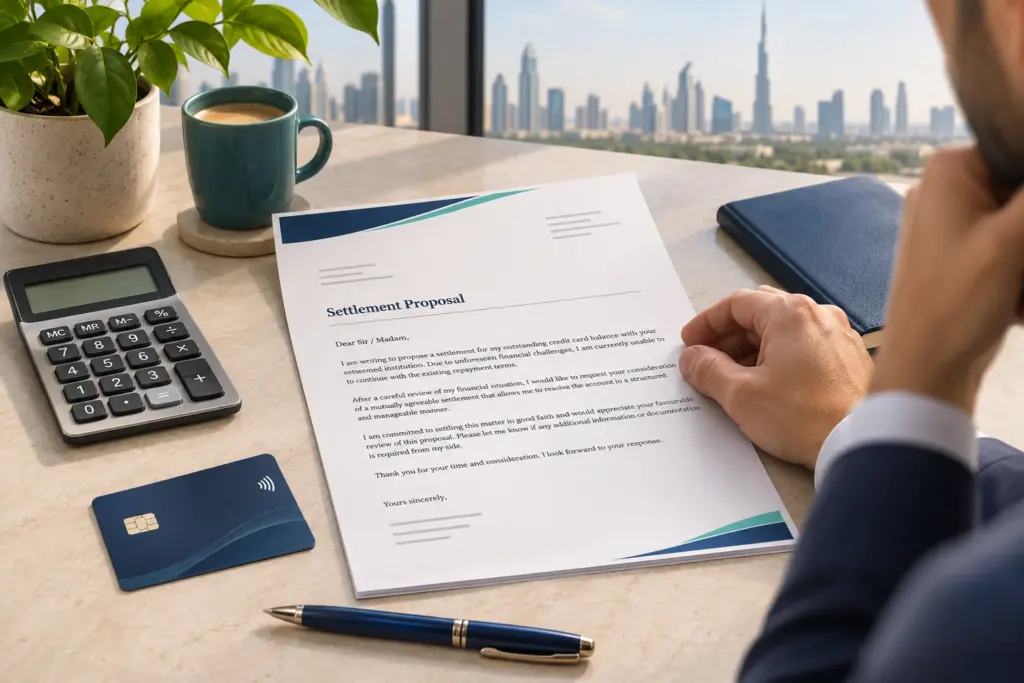
Perhaps your salary has dropped, or finding another job is taking longer than expected. You want to repay your credit card, but the amount due no longer fits your budget. A settlement proposal puts that problem, and an offer you can afford, in writing. Here’s what to include when approaching your lender in the UAE.
First, decide what you are asking for
Do you have enough for a one-time payment, or do you need smaller instalments? Be clear about that before writing. Paying the full balance, asking the bank to accept less and requesting more time are different requests. A smaller instalment may mean paying for longer. A partial payment alone does not wipe out the rest.
There is a basis for opening the conversation. The UAE Central Bank’s Consumer Protection Standards require lenders to give reasonable consideration to alternative arrangements when consumers raise repayment difficulties. They do not require a bank to approve a particular discount or plan. Clause 5.2.4.1.
Get your figures together
Start with your latest card statement and ask for an updated breakdown of what you owe. Gather income evidence, bank statements and a monthly budget. If your salary was cut or your employment ended, include the relevant letter. Check which documents the lender needs.
For a lump-sum offer, explain where the money will come from and when it will be available. If you need instalments, work backwards from your essential expenses and other repayments. Leave yourself some room for an unexpected bill. An offer that stretches you too far will be difficult to maintain.
What goes into the proposal?
Begin with your name, registered contact details and account reference. Use a masked card number in the initial email. Then explain what changed, when it happened and why the current payment is difficult. You do not need a long personal history; give enough detail for the documents and figures to make sense.
State your offer plainly: AED [amount] by [date], or AED [amount] each month from [date]. Say if the money depends on help from someone else.
Ask for written confirmation of any balance or charges to be waived, the deadline, closure documents and credit bureau reporting. Request an acknowledgement and reference number so you can follow up.
A sample credit card settlement letter
This example asks for a reduced lump-sum settlement. Replace the brackets with your details and only offer money you can genuinely make available.
Download the editable settlement letter (Word .docx)
Subject: Credit Card Settlement Request – Account Ending [XXXX]
Dear Collections / Recoveries Team,
I am writing about my credit card account ending [XXXX]. My statement dated [date] shows a balance of AED [amount]. Please confirm the current amount owed.
Since [date], [briefly explain the financial difficulty]. My monthly income is AED [amount], and essential expenses and other repayments total AED [amount].
I can offer AED [amount] by [date] through [funding source], subject to receiving and accepting your written terms. Please consider accepting this as full and final settlement of the account, with the remaining balance and applicable charges waived as agreed in writing.
Please confirm the amount, deadline, payment instructions, treatment of the remaining balance, closure documents and credit bureau reporting. I have attached [documents]. If you cannot accept this offer, please let me know whether another affordable arrangement is available.
Please acknowledge receipt and provide a reference number.
Yours faithfully,
[Name]
[Registered contact details]
[Date]
Hypothetical example – help from a family member
Suppose someone owes AED 60,000 after losing their job. A family member can help with AED 35,000, but only as a one-time payment. The letter should explain this and ask whether that amount would settle the account in full.
These are fictional figures, not an expected discount. If the bank agrees, check what the written terms say about the remaining AED 25,000 and any extra charges. Do not assume that paying AED 35,000 settles everything.
What should you do after submitting?
Keep a copy of what you sent and follow up using the reference number. Ask what you must pay while the bank considers the request. Sending the letter does not itself pause charges, recovery activity or your existing terms. Before paying a settlement amount, verify the approval and payment instructions directly with the lender.
After a revised repayment arrangement is agreed, the Standards require written disclosure within 10 complete business days, including the revised schedule and payment allocation. That period concerns the paperwork after agreement, not approval of your initial request. Clause 5.2.4.4.
If the bank says no, how can Lotus help?
Start by finding out why. Where an account is in arrears and a revised repayment offer is rejected, the lender must give its reasons in writing. Clause 5.2.4.5.
At Lotus Debt Management, we help you look at the bank’s response alongside your income, expenses and debts. From there, we can help organise the documents and prepare a revised proposal that reflects what you can afford. With your authorisation, we also coordinate communication with your lenders.
The discussion may go beyond settlement. We offer budgeting guidance and help explore restructuring or consolidation where feasible. We can also coordinate requests for lower interest or profit rates within a revised repayment plan, subject to lender approval. Look at the fees and repayment period too when comparing the total cost.
Hypothetical interest rate example: Take an unchanged AED 20,000 balance for one month. At 3% a month, the interest would be AED 600. At 1.5%, it would be AED 300, excluding fees. These rates are invented for illustration; they are not a bank offer or a promised result.
We assess each case and explain advisory fees before engagement. Lotus does not lend money or pay off debts for clients. Approval, rate reductions and waivers remain the lender’s decision.
Frequently asked questions
Will settlement remove earlier missed payments?
Paying a settlement does not mean you should expect a clean payment history. Etihad Credit Bureau describes three years of payment history for active and closed facilities. Ask how the arrangement will be reported and check your report afterwards.
What if the credit report is inaccurate?
Check the entry against your settlement and closure documents. If it is wrong or out of date, use the bureau’s Data Correction process. A request to correct an error is different from asking to remove accurate payment history.
Unsure what you can reasonably offer? Contact Lotus Debt Management to discuss your repayment position before putting a proposal together.
This article provides general information, not financial or legal advice. Both examples are hypothetical. If legal proceedings already exist, obtain advice on your specific case.
References
Sources support the factual guidance. “n.d.” means no publication date is stated. Sources accessed on 10 November 2026; Lotus service information rechecked on 11 November 2026.
Central Bank of the UAE. (2021). Consumer Protection Standards. Clauses 5.2.4.1, 5.2.4.4 and 5.2.4.5. https://rulebook.centralbank.ae/en/rulebook/consumer-protection-standards
Etihad Credit Bureau. (n.d.). Credit Report – Individual. https://etihadbureau.ae/en/Individual/CreditReport
Etihad Credit Bureau. (n.d.). Data Correction – Personal. https://etihadbureau.ae/Support/DataCorrectionPersonal
Lotus Debt Management. (n.d.). Frequently Asked Questions. Advisory services, client authorisation and lender approval. https://lotusadvisoryuae.com/faqs/